The FXIFY Trading Desk Brief: Week of 14 September 2026
Situation Report The September 15–16 FOMC meeting is the first SEP meeting under Warsh’s chairmanship with a live hike debate. The committee will have August…
Situation Report
The September 15–16 FOMC meeting is the first SEP meeting under Warsh’s chairmanship with a live hike debate. The committee will have August NFP, August PPI, and August CPI all in hand before voting on Wednesday 16 September.
Here is where things stand heading into Monday. August NFP came in at +162,000, beating the 55,000 consensus by 107,000 and snapping a two-month run of deeply weak data that included July’s -23,000 and June’s revised +20,000. Prior months were revised up a combined 55,000. Unemployment held at 4.1%. Participation edged up to 61.6%. The August NFP beat reduced the labour-market argument against a September hike.
Thursday’s PPI was mixed. Headline PPI rose 0.4% month-on-month in August, accelerating the annual rate to 5.4%, slightly above the 5.3% forecast. Core PPI, excluding food and energy, rose only 0.2% month-on-month, below the 0.3% forecast, and 4.6% year-on-year. The report pushed Treasury yields higher and was enough to keep September hike expectations elevated.
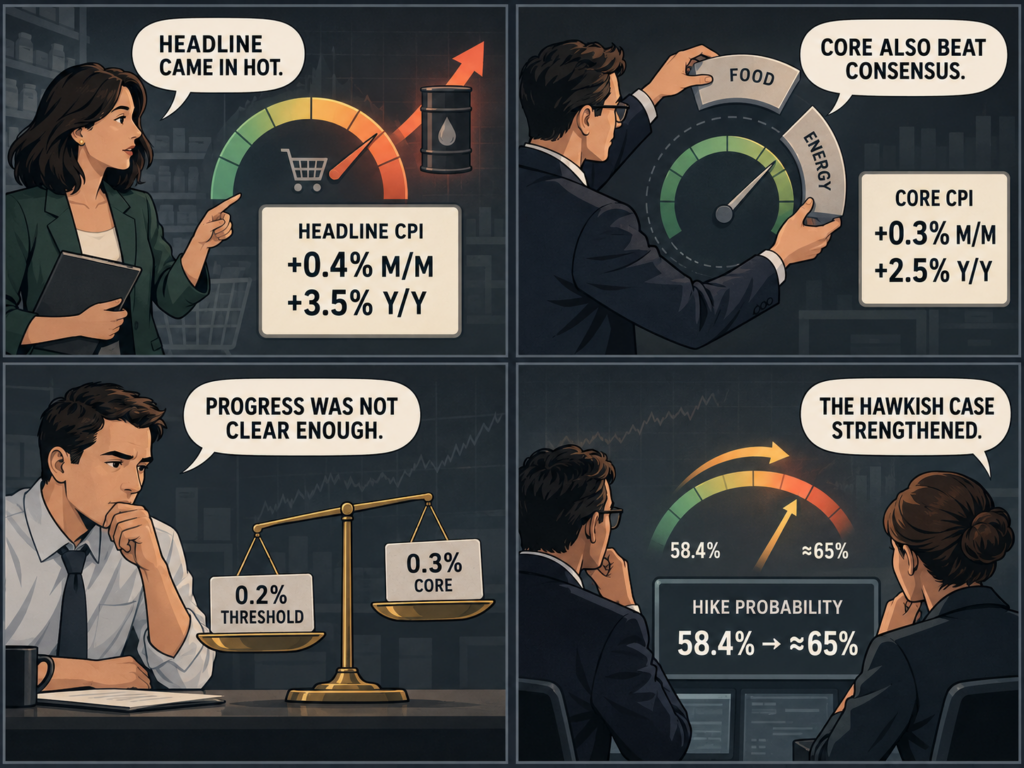
Friday’s CPI delivered above the 0.2% consensus on core. Headline held at 3.4% YoY and rose 0.4% MoM, the largest monthly increase since May. Core CPI rose 0.3% MoM, one tenth above expectations and its largest monthly advance since April. Following the release, CME FedWatch briefly hit 91% probability of a September hike before settling near 87%, up from 72% on Thursday per Reuters citing CME Group data. As of Sunday 13 September, Polymarket and CME futures both price the hike in the 80–90% range. A September hike is now the overwhelming market base case.
The FOMC votes on Wednesday, 16 September.
Last Week in Review
NFP August: +162,000, well above consensus
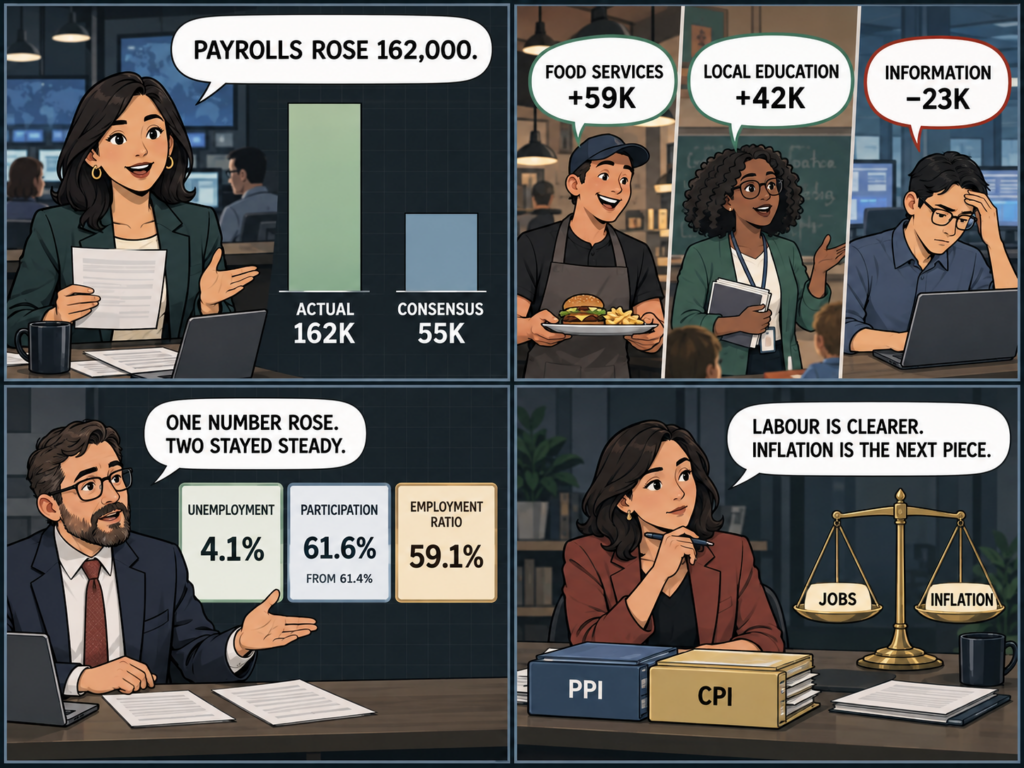
The Bureau of Labor Statistics reported on 4 September that nonfarm payrolls rose 162,000 in August, far exceeding the Dow Jones consensus of 55,000 and reversing two consecutive months of deeply soft data. Employment increased primarily in food services and drinking places and local government education. The information sector shed jobs. Prior months were revised upward: combined June and July revisions added 55,000 jobs back to the reported figures.
The unemployment rate remained at 4.1%. The labour force participation rate edged up to 61.6% from 61.4% in July, the first improvement since May. The employment-population ratio was little changed at 59.1%.
Waller had said on 3 September that he would favour holding rates if August inflation showed progress. The NFP print addressed the labour side of the mandate clearly. It did not address inflation. PPI landed Thursday and CPI landed Friday. Both are covered below.
PPI August: hot headline, soft core
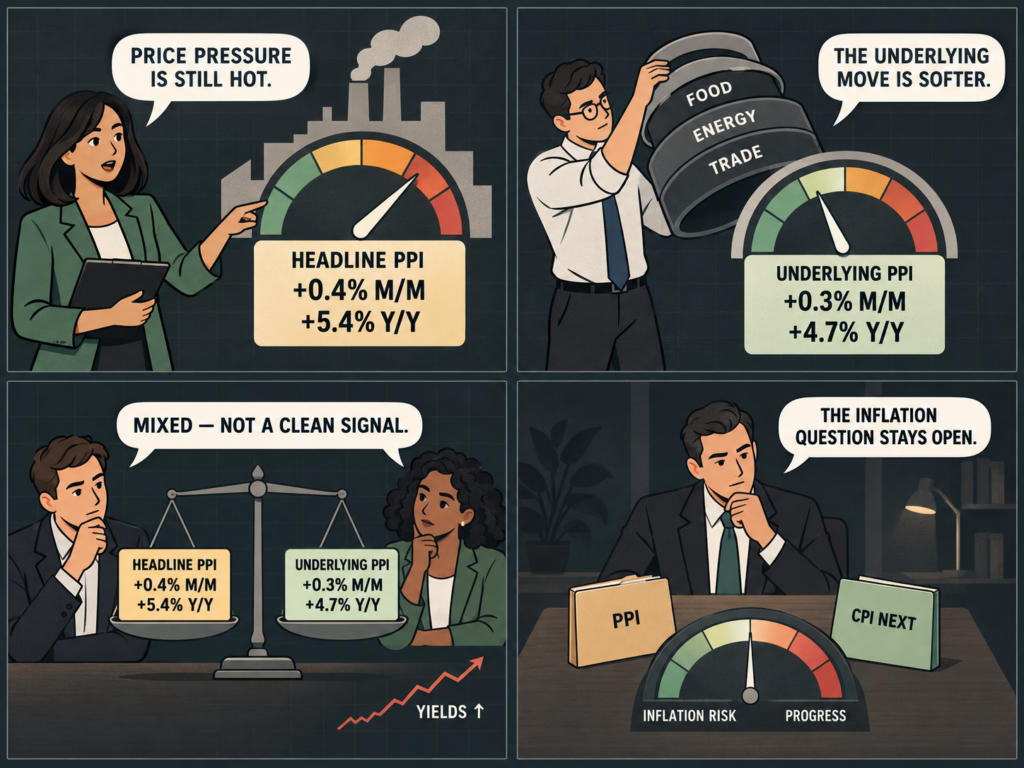
The BLS released August PPI on Thursday 10 September. Headline PPI rose 0.4% month-on-month, matching expectations, with the annual rate accelerating to 5.4%, slightly above the 5.3% forecast. Core PPI excluding food and energy rose only 0.2% month-on-month, below the 0.3% forecast, with the annual rate at 4.6%. The mixed result kept inflation concerns alive without delivering an unambiguous signal. Treasury yields moved higher on the day.
This Week’s Events
Friday, 11 September — US CPI August (Result) | Impact: CRITICAL
What Happened
August CPI landed at 8:30 AM ET on Friday, the last major inflation data point before the FOMC votes on Wednesday.
The Bureau of Labor Statistics reported that headline CPI rose 0.4% in August, its largest monthly increase since May, and held at 3.4% year-on-year, unchanged from July. Gasoline prices jumped 3.9% and accounted for more than one-third of the monthly headline increase. Shelter costs accelerated, rising 0.3% after a 0.1% increase in July.
Core CPI, excluding food and energy, rose 0.3% month-on-month, one tenth above the 0.2% consensus and its largest monthly advance since April. The annual core reading came in at 2.4% year-on-year.
The above-consensus core reading was the signal the hawkish camp needed. Waller had explicitly conditioned his hold preference on August inflation showing continued progress. A core reading of 0.3% MoM does not satisfy that condition. Following the release, CME FedWatch briefly hit 91% probability of a September hike before settling near 87%, up from 72% on Thursday per Reuters citing CME Group. KPMG Chief Economist Diane Swonk wrote on LinkedIn that the hike was needed because the “burn of inflation is just too costly” and added that the vote could be unanimous.
What It Means for Wednesday
Three data points are now in the FOMC’s hands: NFP beat by 107,000, PPI headline above forecast at 5.4% YoY, and core CPI printing 0.3% MoM with the annual rate at 2.4%. The labour market held up. Producer costs are elevated. Consumer inflation reaccelerated month over month. All three point in the same direction. The committee votes in two days.
Wednesday, 16 September — FOMC Rate Decision, SEP, and Press Conference (USD) | 6:00 PM GMT
The Setup
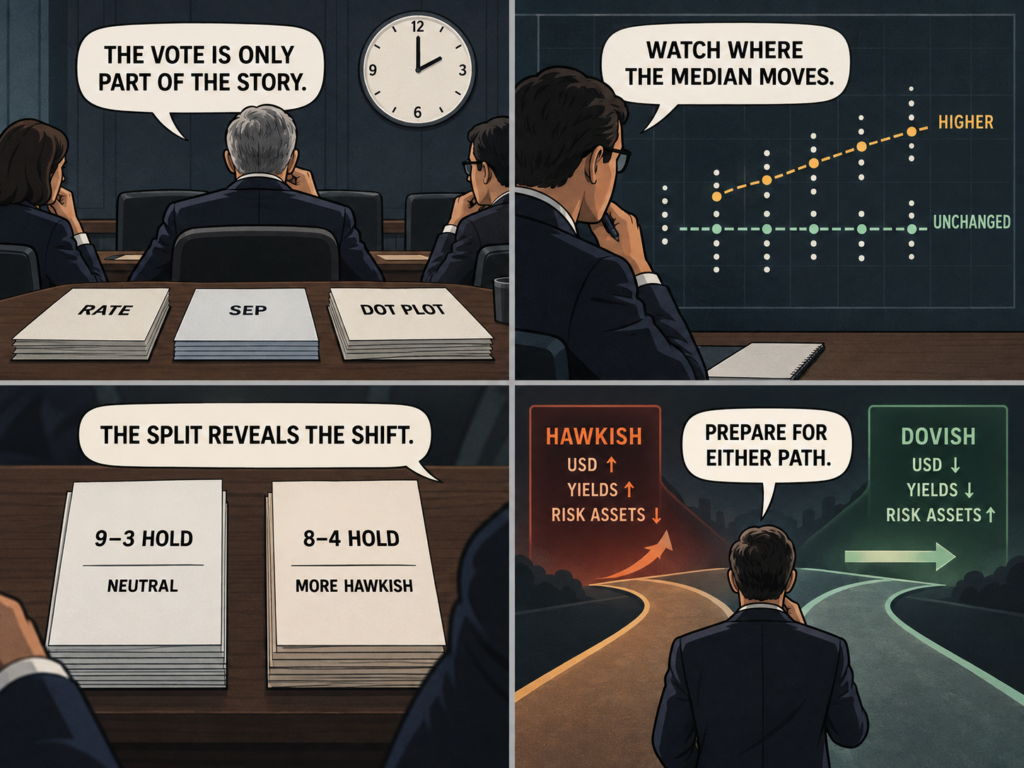
The Federal Reserve announces its September rate decision at 2:00 PM ET on Wednesday. This is an SEP meeting: the committee releases updated economic projections, a new dot plot, and Chair Warsh holds a full press conference at 2:30 PM ET.
The rate decision itself will be significant. But in an SEP meeting, the dot plot and the updated economic projections carry equal weight to the vote. The June dot plot signalled at least one hike before year-end. If the September dot plot moves the median projected rate higher, or if more members cluster around a year-end rate above 3.75%, that signals further tightening is coming regardless of what happens Wednesday. If the dot plot softens, it signals the committee is shifting toward a hold-and-watch posture.
Warsh has avoided providing forward guidance in his previous two press conferences, consistent with his stated approach of letting data drive decisions rather than pre-committing to a path. A Jackson Hole-style directional message from the podium on Wednesday would be unusual, but given the level of internal division this cycle, traders will be listening for any deviation from his standard non-guidance stance.
Three members voted to hike at the July 29 meeting: Hammack, Kashkari, and Logan. The minutes from that meeting showed broader hawkish sympathy beyond those three. If today’s CPI lands hot, the vote split could widen further.
The Key Number
The vote count. A 9-3 hold is neutral. An 8-4 hold signals the committee is moving toward a hike. Any hike sends an immediate signal.
The Split
Hawkish outcome: Rate hike to 3.75–4.00%, or hold with dot plot showing median year-end rate above 3.875%. USD likely strengthens. Treasury yields rise. Risk assets may face pressure.
Dovish outcome: Hold at 3.50–3.75% with dot plot unchanged or lower. USD likely weakens. Yields fall. Risk assets may respond positively..
The Call
Since Jackson Hole, the data flow has been broadly supportive of the hawkish case. NFP beat by 107,000. PPI came in above forecast on the headline. Core CPI printed 0.3% MoM, its largest monthly advance since April. September hike probability is approximately 87% heading into Wednesday, the highest it has been this cycle and well above a coin flip.
The internal logic of the FOMC’s decision depends heavily on two things Warsh said explicitly. First, at Jackson Hole: “We must be confident that underlying inflation is moving to our objective clearly and at sufficient speed.” Core CPI at 0.3% MoM does not suggest the pace is sufficient for the hawks. Second, Waller’s conditional: he would favour a hold if August inflation shows continued progress. A monthly core acceleration to 0.3% from 0.2% does not meet that bar.
TD Securities, following the CPI release, now expects a total of three rate hikes in this cycle, with October and January as the next two after a September move. Deutsche Bank expects two hikes, September and December, taking the rate to 4.00–4.25%. KPMG’s Diane Swonk raised the possibility of a unanimous vote, which would be the clearest possible statement of institutional commitment to the inflation mandate.
Watch the dot plot. With TD Securities, Deutsche Bank, and Bank of America all projecting further hikes beyond September, the updated December and 2027 rate projections in Wednesday’s SEP will signal whether the committee is aligned on the rate path ahead or still internally divided. A dot plot that shows a majority projecting the rate above 4.00% by year-end would send as strong a signal as the decision itself.
Watch USD/JPY. The pair fell sharply after Waller’s 3 September remarks and has recovered substantially following the NFP beat and CPI overshoot. A hike on Wednesday with a hawkish dot plot could push it significantly higher. A hold with softened guidance could challenge the recovery.
Watch gold. It has moved in the opposite direction of September hike expectations throughout this cycle. At 87% hike probability, gold has already partially priced in the move. The variable is the dot plot: a hawkish path beyond September would likely weigh further. A softer-than-expected 2027 rate projection could provide support.
Calendar
| Date | Event | CCY | Time GMT | Impact |
|---|---|---|---|---|
| Fri 11 Sep | Consumer Price Index (August) — RELEASED | USD | 12:30 PM | CRITICAL |
| Wed 16 Sep | FOMC Rate Decision | USD | 6:00 PM | CRITICAL |
| Wed 16 Sep | FOMC Economic Projections (SEP) | USD | 6:00 PM | CRITICAL |
| Wed 16 Sep | Warsh Press Conference | USD | 6:30 PM | CRITICAL |
Risk Notice
This week carries two high-impact events within five days of each other. CPI this morning and the FOMC decision on Wednesday. Both events are capable of generating significant multi-directional price action across USD pairs, bonds, equities, and commodities. Make sure you understand how your FXIFY account drawdown rules work before trading around either release. For more on managing volatility as a funded trader, see our guides on trading styles for funded traders and how news events affect prop traders.